Category: Commercial debt recovery · Topic: Workflow evaluation · ·
Commercial Debt Collection Process: A Practical Workflow for Business Owners
A practical commercial debt collection process for business owners: organize records, assign ownership, follow up clearly, and evaluate next steps.
Short answer
A commercial debt collection process is a repeatable way to move an overdue business invoice from “something is late” to a documented next action. Start by checking what your records show, give one person responsibility for the next communication, contact the appropriate business team with a clear question, and log what happens.
A commercial debt collection process is a repeatable way to move an overdue business invoice from “something is late” to a documented next action. Start by checking what your records show, give one person responsibility for the next communication, contact the appropriate business team with a clear question, and log what happens. If the issue remains unresolved, leadership can review the portfolio context and decide whether an outside receivables-workflow conversation is useful.
This is general operating context for business-purpose receivables only. It is not a decision about any individual matter, and it does not promise payment, timing, or a particular outcome.
Key Takeaways - Begin with the records, not an assumption: verify the invoice, contact route, transaction context, and internal notes. - Give one person the next action while finance, account, and operations teams supply the facts they own. - Treat routing gaps, missing information, and discrepancies as branches to investigate, not reasons to repeat the same message. - Review outside support as a portfolio-level operating question, not an automatic escalation. - Technology can organize routine work, but people remain responsible for review, exceptions, and account-specific next steps.

Before you begin: set the commercial boundary and make the work visible
A useful process begins by naming what it is for: managing unpaid invoices or receivables arising from a business relationship. It is not a public place to sort through individual account questions or share account-level detail. This guide stays focused on organization-level workflow context; it does not determine how any particular obligation should be classified or handled.
Make the workflow visible before anyone reaches out. An internal working view can show an invoice or reference, customer organization, balance category, status, last action, responsible owner, and next review point. That view is an organizational aid. It is not a public record, a decision engine, or a substitute for qualified guidance when a situation requires it.
A simple visible workflow also prevents the overdue list from becoming a set of isolated reminders. It helps the team see which matters have clean records, which need a new contact route, and which are waiting on someone else’s facts. For broader context on connecting organized follow-up to cash-flow planning, see PayClear’s broader business debt recovery strategies.
Step 1: Verify the receivable record and assemble a clean working file
Start with what the business’s own records show. Confirm the customer organization, the appropriate business contact route, invoice or reference, due-date information, order or agreement context, delivery or service-completion context where applicable, recorded credits or payments, and current internal notes. A wrong recipient, an unclear reference, incomplete fulfillment information, or an unposted payment can change the next operational action. Allianz Trade recommends checking invoice routing, payment terms, and delivery context before moving beyond internal efforts (S6).
Build a contained internal packet
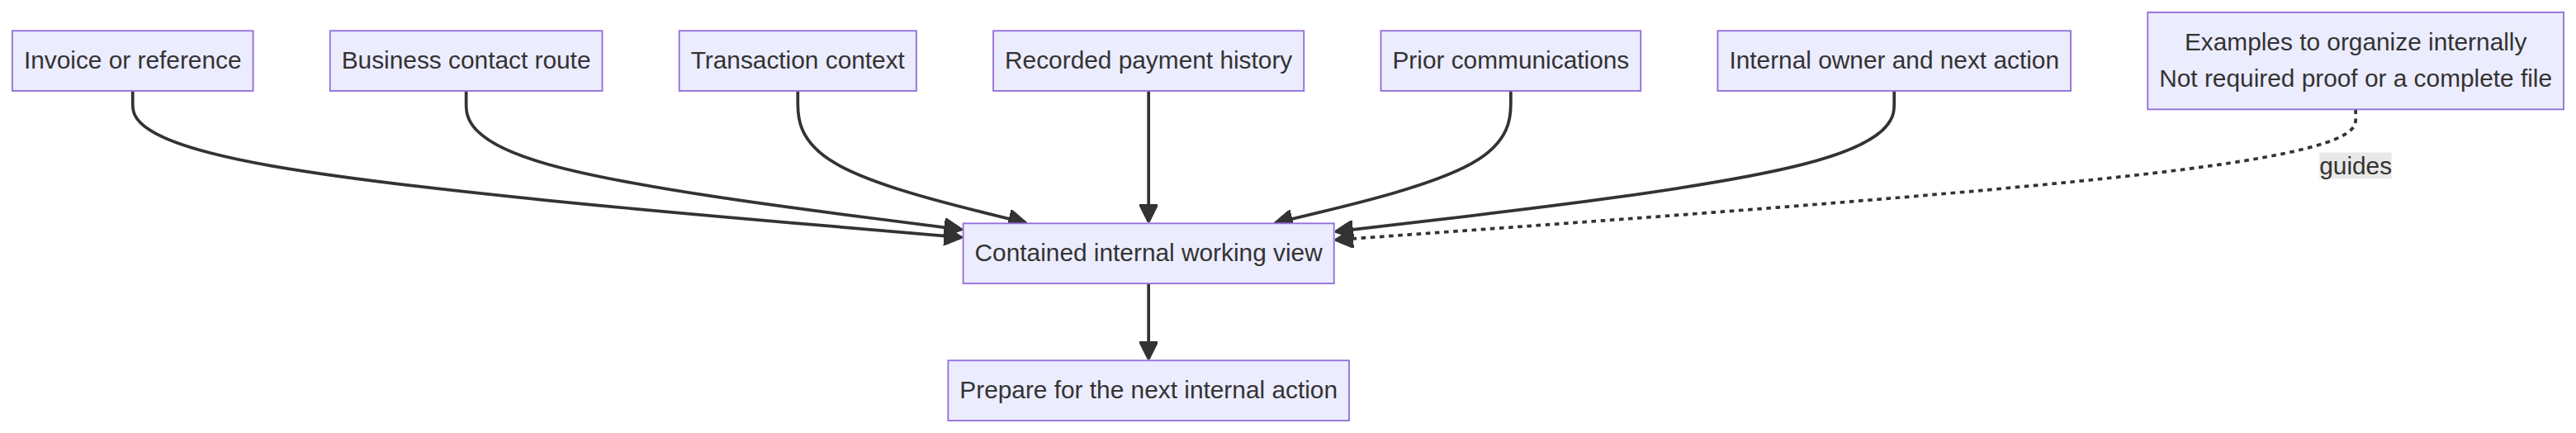
Bring the materials your team already has into one controlled internal location: invoices, statements, applicable business documents, delivery or service records, payment records, and prior communications. The IRS lists invoices, receipts, deposit slips, paid bills, and payment records among examples of supporting business documents, and advises businesses to organize records in an orderly way for their books (S1; S2). Those are business recordkeeping examples, not a claim that a particular packet is complete for every purpose.
Keep the packet inside the organization’s agreed information-sharing process. Do not post account numbers, consumer identifiers, payment information, documents, or other sensitive details in public web forms or public comments. A useful file makes it easier for internal teams to answer operational questions without turning a public inquiry into an account-level exchange.
For a related discussion of records and relationship-aware business follow-up, see PayClear’s B2B receivables context.
Step 2: Assign an owner and a realistic next action
An aging list becomes manageable when every next action has an owner. Assign one person to coordinate the next communication. Then identify the people who can provide the underlying facts: finance or accounts receivable for records, sales or account management for relationship context, operations for fulfillment details, and leadership for exceptions or approvals.
This does not require a universal organization chart. It means the team knows where an issue goes instead of letting several people send overlapping messages or assuming someone else is handling it. Atradius describes credit management as an ongoing process involving account monitoring, consistent procedures, open communication, and collaboration among sales, finance, and customer-service teams (S7). NACM likewise describes a collections policy as a place to define contact practices, dispute handling, and when to consider outside support (S11).
Use statuses instead of a one-size-fits-all clock
A review rhythm should fit the business’s terms, relationships, documentation status, and approval path. Instead of treating every invoice as though it follows the same calendar, use clear working statuses such as ready to contact, awaiting information, discrepancy under review, next action logged, or needs leadership review. A status tells the team what is known and who owns the next move without implying a fixed timetable or outcome.
Step 3: Contact the appropriate business person with a clear question
The first follow-up should be factual, specific, and designed to discover a problem that the team can address. Identify the invoice or reference, ask whether it reached the appropriate business team, and invite the recipient to identify a routing, documentation, delivery, or payment-processing issue. The goal is a clear next action, not a script that assumes why an invoice is overdue.
This approach is consistent with Allianz Trade’s recommendation to check obvious invoice and delivery issues and contact the customer to understand invoice, delivery, accounting, or cash-flow concerns before progressing beyond internal efforts (S6). Keep the conversation respectful and tied to the business record. Avoid making assertions that the available information does not support.
Log the substance of each touchpoint
For every contact, record the date, channel, internal owner, external business role or contact, issue raised, any information requested or provided through an appropriate channel, the stated next action, and who owns the follow-up. NACM identifies documentation of collection efforts and accurate order-to-cash information as components of commercial collection work (S4).
A concise log reduces repeated questions and makes a portfolio review understandable. It also gives the next internal owner context if the relationship changes hands. The log should describe what happened; it should not turn a business process into assumptions about a specific account.
Step 4: Route discrepancies and missing information before repeating the request
Not every past-due invoice is a simple follow-up problem. When an issue appears, route it to the person who can investigate it rather than sending the same request again. A defined branch keeps the team responsive and prevents conflicting messages.
Use issue branches that lead to a responsible owner
- Invoice-routing issue: resend or redirect using the organization’s approved business channel.
- Missing documentation question: ask the source owner to locate the relevant operational record.
- Delivery or service discrepancy: send the context to the team that can review the transaction facts.
- Payment-processing or credit question: reconcile the internal record before the next communication.
- Commercial relationship exception: involve the designated account, finance, or leadership owner.
- Situation needing specialized input: pause the general workflow and use the organization’s qualified internal or external route.
NACM notes that a collections policy can address disputes or deductions and can define how the process is prioritized; Atradius similarly emphasizes consistent procedures and cross-functional communication (S11; S7). These sources support the operating principle of routing and documenting issues, not a conclusion about the merits of any discrepancy.
Keep relationship context visible while the issue is open. A customer relationship and an overdue balance can both be real. An owner, a status, and an agreed next review point give the business a way to address the facts without losing track of the relationship.
Step 5: Evaluate the next operating path at the portfolio level
Outside support is a decision-readiness question, not a mandatory next stage. Leadership can consider it when internal capacity, reporting, approvals, exception handling, or the pattern of unresolved work no longer fits the organization’s needs. The U.S. Chamber of Commerce’s CO— resource frames a collection agency as one possible option when a business repeatedly cannot obtain payment and notes that businesses may assess a prospective partner’s reporting and technology capabilities (S8). That is background for an operating discussion, not an endorsement, threshold, or prediction.
Before any conversation, ask:
- Is the record packet organized enough for a responsible review?
- Has the team captured the latest known issue, contact path, and attempted next action?
- Does the organization need more internal capacity, clearer reporting, first-party support, or a broader workflow discussion?
- What approval, exception-handling, and information-sharing expectations matter to the business?
These questions keep the focus on portfolio context. For a high-level explanation of the evaluation path, see how a commercial receivables workflow is evaluated. No question on this list determines whether a matter will be accepted, handled, or resolved.
Step 6: Review the process before the next invoice cycle
A review is useful even when a particular balance remains open. Look for operating patterns: Were invoices missing key context? Did a handoff stall? Did a contact route change? Did ownership become unclear? Then adjust the internal checklist, intake fields, or review process for the next cycle.
Allianz Trade recommends repeatable invoicing and reminder processes, document availability, and a paper trail; Atradius describes ongoing monitoring and consistent procedures as parts of credit management (S5; S7). Use operational dimensions such as record completeness, aging visibility, status movement, time to a defined next action, and reporting clarity. They help teams evaluate the workflow; they are not recovery results.
Where technology can help—and where people remain responsible
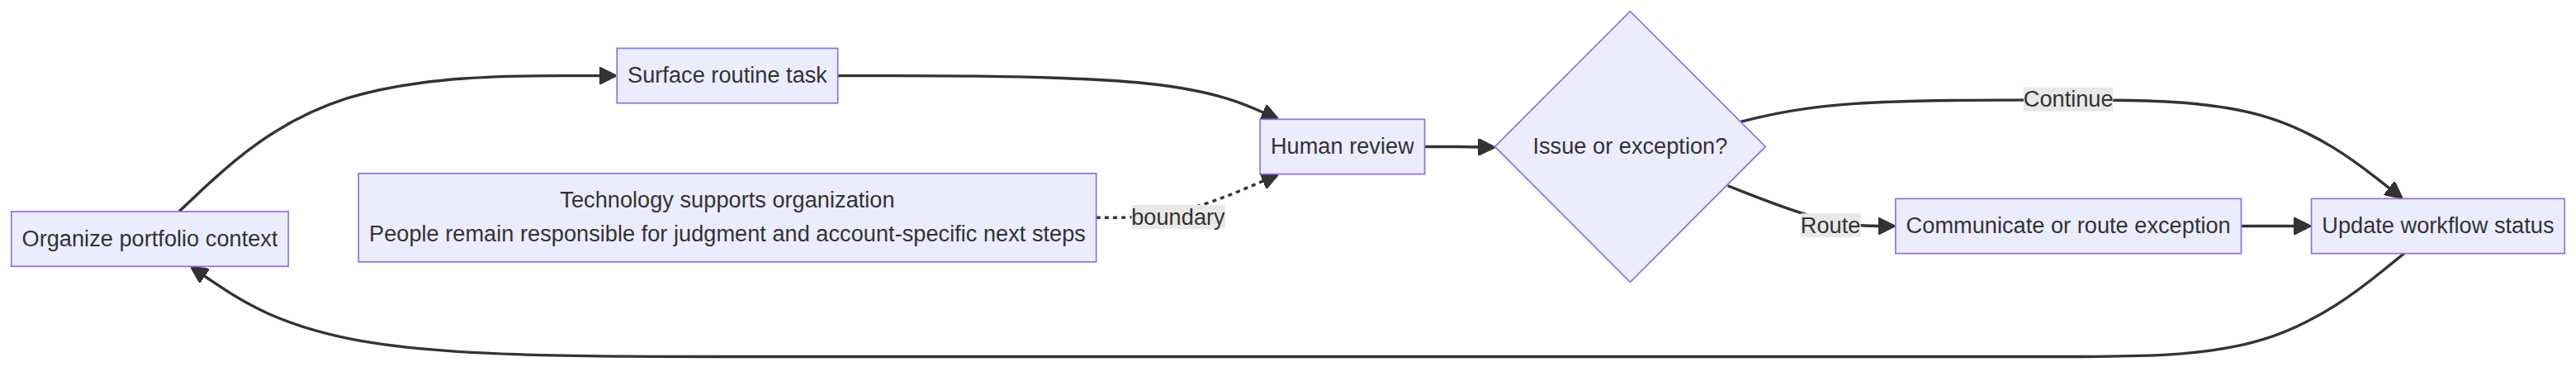
Workflow tools can organize portfolio context, surface routine follow-up work, prepare summaries, and make handoffs easier to see. Those are support functions. They do not replace the people who review fit, interpret exceptions, choose communications, and remain responsible for account-specific next steps.
NIST’s AI Risk Management Framework says human judgment should be used when selecting trustworthiness metrics and thresholds, and that defined human roles and responsibilities matter in human-AI configurations (S9). In this workflow, that means AI may support organization and preparation, with human review of exceptions and decisions. It does not mean AI makes a collection decision or validates an account.
For a related perspective, see technology as workflow support and PayClear’s article on technology-assisted collection workflows.
Discuss the workflow after the internal review
If your organization has completed the record, ownership, and issue-review steps and wants to discuss a commercial receivables workflow, PayClear can begin with a business-level inquiry. The public inquiry is business-level only and must not receive account numbers, consumer identifiers, payment information, documents, or other sensitive details. Share only the organization and high-level operating context; a person reviews the business purpose, portfolio context, exceptions, and appropriate next steps.
Frequently asked questions
What is the first step in a commercial debt collection process?
Confirm what your business records show before outreach: the invoice or reference, business contact route, transaction context, recorded payments or credits, and current internal notes. This creates a factual starting point for the next action without deciding the outcome.
What should a business organize before discussing an overdue receivable?
Organize the invoice or reference, business contact route, transaction context, payment history, prior communications, and the internal owner for the next action. These are operational examples, not a claim that the file is complete for every situation.
How should a business handle an invoice discrepancy in this workflow?
Route the discrepancy to the person who can investigate it, record the status and next action, and avoid repeating the same request while necessary information is unresolved. That keeps the work coordinated and gives the customer organization a clear path to surface a real issue.
When should a business evaluate outside receivables support?
Consider a portfolio-level discussion when leadership needs to evaluate capacity, reporting, approvals, exception handling, or workflow fit. There is no universal referral age or automatic next step in this guide.
This guide provides general commercial workflow context for business owners and authorized decision-makers. It does not address personal or household debt, public account questions, payment processing, debt settlement, legal options, or account-specific decisions. For neutral educational reading, explore more receivables briefings.
Sources
- S1. Internal Revenue Service, Recordkeeping (retrieved 2026-10-04).
- S2. Internal Revenue Service, What kind of records should I keep (retrieved 2026-10-04).
- S4. National Association of Credit Management, Commercial Collections: An Overview (retrieved 2026-10-04).
- S5. Allianz Trade US, Strategies and Techniques to Improve Accounts Receivable Collection Processes (retrieved 2026-10-04).
- S6. Allianz Trade, Business debt collection: how to recover unpaid invoices (updated 2024-07-23; retrieved 2026-10-04).
- S7. Atradius, Understanding credit management: key concepts and best practices (published 2025-10-09; retrieved 2026-10-04).
- S8. U.S. Chamber of Commerce CO—, What Is a Debt Collection Agency, and When Do You Need One? (published 2026-08-11; retrieved 2026-10-04).
- S9. National Institute of Standards and Technology, Artificial Intelligence Risk Management Framework (AI RMF 1.0) (published 2023-01; retrieved 2026-10-04).
- S11. National Association of Credit Management, Collections Policy (retrieved 2026-10-04).