Category: Commercial debt recovery · Topic: Small-business receivables prioritization · ·
Small Business Debt Recovery: A Practical Workflow for Owners
Small-business debt recovery: prioritize overdue receivables, assign follow-up ownership, and assess next steps without assuming an outcome.
Short answer
Small business debt recovery can start with a simple, owner-led review of overdue business-purpose receivables: what the organization has recorded, which questions remain open, and who has time to own the next internal step. The goal is to help a small team prioritize its work and decide whether a different workflow is worth discussing—not to infer a legal outcome, set a universal escalation timetable, or predict what will be recovered.
Small business debt recovery can start with a simple, owner-led review of overdue business-purpose receivables: what the organization has recorded, which questions remain open, and who has time to own the next internal step. The goal is to help a small team prioritize its work and decide whether a different workflow is worth discussing—not to infer a legal outcome, set a universal escalation timetable, or predict what will be recovered.
Key takeaways
- Review overdue receivables alongside open questions and the team's available follow-up capacity.
- Use the aging view as one management signal, not as an automatic escalation rule.
- Assign a clear internal owner before adding another workflow or outside support.
- Keep public B2B inquiries organization-level; use the separate account-information route for consumer questions.
An editorial illustration of a small business reviewing receivables as an operating question, not an account-level decision.
Start with the business decision
The useful first question is not “How old is this invoice?” by itself. Ask what the team needs to decide: Which group of business receivables needs attention? Is a billing or payment reference unclear? Who can resolve the open question? Does the organization have time to continue its current follow-up workflow, or would it benefit from evaluating a different business process?
This guide is for organization-level commercial receivables. It is not instructions for personal, family, or household debt, and it cannot determine the status, validity, or recoverability of a particular account. For a broader introduction to the commercial category, see PayClear's B2B receivables guide.
Build a small-team priority view
A basic accounts-receivable aging view groups outstanding invoices by how long they have been overdue. The U.S. Chamber of Commerce describes aging as a management tool for organizing open invoices into age groups; its example ranges are illustrative, not a required timetable. A small business can read its own aging view alongside a few other operating signals:
| Portfolio signal | Internal question | What the signal does not decide |
|---|---|---|
| Aging groups used by the business | Which set of receivables needs an owner's review first? | A required contact date or a guaranteed outcome |
| Recorded balance and invoice count | What scale of work is the team trying to manage? | Whether a specific balance is correct or recoverable |
| Open business questions | Is a payment reference, credit, billing contact, or delivery question still unresolved? | The answer to a disputed or unclear item |
| Team capacity and ownership | Who can take the next business-process step, and when can the team review it? | A universal staffing model or escalation rule |
| Reporting need | What portfolio-level view would help the organization manage its work? | A service feature or reporting commitment not separately confirmed |
Age is only one input. A newer receivable may have an unresolved reference; an older one may already have a clear internal follow-up. Keep the facts and questions distinct so the team can choose a next step without treating an age band as an account decision.
Make follow-up ownership visible
For a small team, work can stall when several people assume someone else owns the next follow-up. Name one internal coordinator for the business view, then identify the function best placed to answer each open question—such as finance for a posted-payment reference or operations for a delivery record. The coordinator can keep a short, factual status list; the person with the relevant knowledge can verify the underlying business record.
The U.S. Small Business Administration's general cash-flow guidance discusses prompt invoicing and maintaining a follow-up system. It does not set a universal contact cadence or tell a business when to escalate. Use the process and review rhythm that fit the organization's own records, operations, and responsibilities.
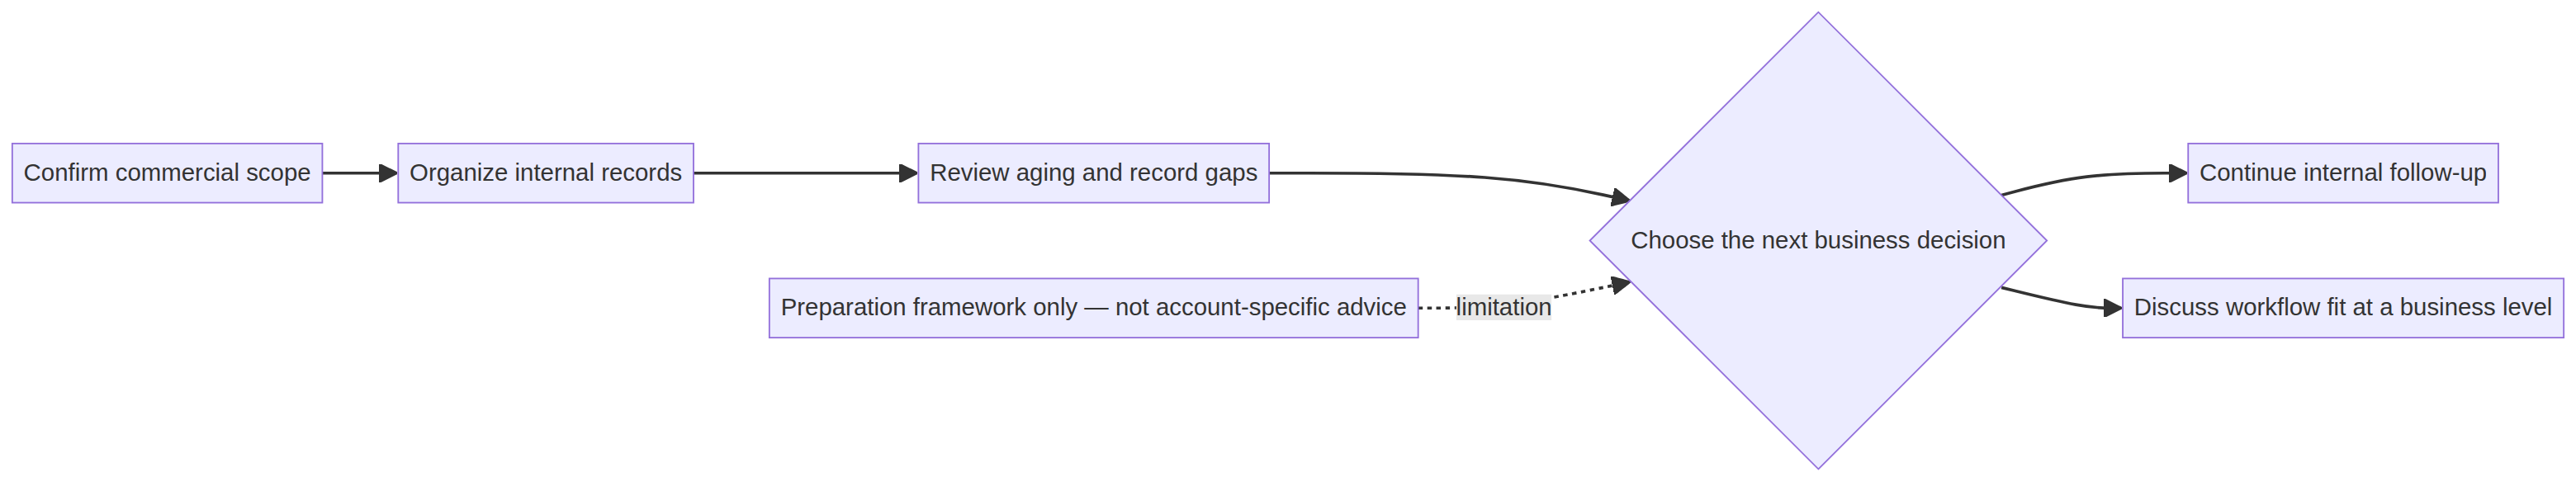
Illustrative workflow only. The sequence helps organize internal work; it does not prescribe a timetable or predict a result.
Decide what stays in-house and what workflow to evaluate
The right operational choice depends on the team's own circumstances. A business may continue internal follow-up when the next task is clear and the responsible person has capacity. It may first need to resolve an internal question or correct its records. If the volume of work, staffing demands, or need for portfolio-level reporting is prompting a process review, the organization can compare possible workflows against its requirements.
This is a workflow-fit question, not a conclusion about whether a particular receivable should be placed or what result an outside provider will achieve. PayClear's How It Works page describes the business-level evaluation conversation. For the more detailed record categories and question-log approach, see the separate commercial receivables documentation guide.
Keep a public business inquiry high level
PayClear's public B2B form uses organization and portfolio fields plus a closed-list workflow-topic selection; it has no free-text message box or document-upload field. Do not try to submit invoices, account numbers, consumer identifiers, payment information, detailed communications, disputes, or other sensitive information through a public inquiry. Any later exchange of detailed records requires a separately agreed, appropriate process after human review.
This commercial guide is not an account-information or dispute path. A person seeking information about an individual account, or asking a personal, family, or household debt question, should use the separate Account Information route, not the B2B inquiry.

Boundary illustration only; it does not describe an upload portal or a specific data-exchange process.
Review the workload on the organization's own rhythm
A repeatable review can stay brief: look at the organization's current aging groups, identify material open questions, confirm who owns each next internal task, and note whether the workflow still fits available team capacity. Keep that rhythm tied to the business's own operating needs rather than a rule borrowed from a generic checklist.
Technology may help teams organize approved portfolio context and handoffs. People remain responsible for reviewing exceptions, business decisions, and account-specific matters. PayClear's technology and compliance overview explains that distinction.
Discuss workflow fit after the internal review
If your organization wants to discuss a business-level receivables workflow after reviewing its priorities and internal capacity, you can start an organization-level inquiry. That inquiry does not determine placement, acceptance, an account decision, or a recovery result. Keep the submission at organization level and do not include account-level or sensitive details.
Frequently asked questions
What should a small business review first?
Start with the business's current receivables view, the open questions attached to the work, and the person or function responsible for the next internal step. The right starting point varies by organization; this guide does not assess an individual account.
How should a small business use an accounts-receivable aging view?
Use the organization's own age groups to understand the distribution of open invoices, then compare that view with recorded balances, unresolved business questions, and team capacity. Aging is a management signal, not a universal escalation timetable.
Does an older invoice automatically mean that a business should escalate it?
No. Age by itself does not establish the underlying facts or determine a next step. A business can review its records, open questions, ownership, and operating priorities before choosing how to proceed.
Can I send an invoice or account document through the public inquiry?
No. The public B2B form has no document-upload or free-text narrative field. Do not place account numbers, consumer identifiers, payment details, invoices, or other sensitive material in the public inquiry. Any later exchange must use a separately agreed, appropriate process.
Is this guide for personal or household debt?
No. It addresses business-purpose commercial receivables only. For an individual account question or a personal, family, or household matter, use the separate Account Information route.
Sources and limitations
- U.S. Chamber of Commerce CO—, What Is an Accounts Receivable (AR) Aging Report? (published January 9, 2023; accessed October 4, 2026). Used for the general explanation of aging as an organizing view; example date ranges are not adopted as a prescribed schedule.
- U.S. Small Business Administration, How Net 30 Accounts Help Conserve Business Cash Flow (published September 13, 2016; accessed October 4, 2026). Used only for the general point about prompt invoicing and maintaining a follow-up system, not as a universal cadence or escalation rule.
- Internal Revenue Service, Recordkeeping (page last reviewed May 1, 2026; accessed October 4, 2026). Used for general business recordkeeping context, not as a debt-collection checklist.
- Federal Trade Commission, Start with Security: A Guide for Business (accessed October 4, 2026). Used for general data-minimization context; this guide does not assert that PayClear has a particular security certification or data-handling standard.
This article is general business information, not legal, accounting, tax, or account-specific advice. It does not decide whether a receivable is valid or predict a recovery outcome.